


Page 24 - october22_previewaa.indd
P. 24
TAP TIMES       -24-                                     OCTOBER 2022


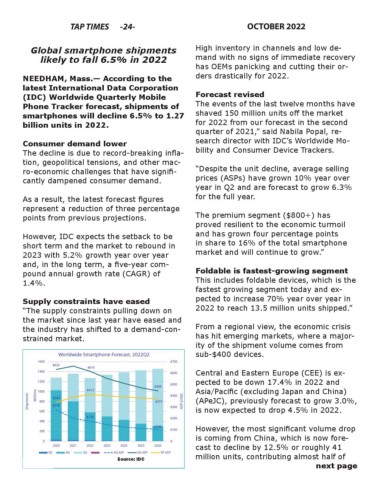
           Global smartphone shipments                          High inventory in channels and low de-
              likely to fall 6.5% in 2022                       mand with no signs of immediate recovery
                                                                has OEMs panicking and cutting their or-

        NEEDHAM, Mass.— According to the                        ders drastically for 2022.
        latest International Data Corporation
        (IDC) Worldwide Quarterly Mobile                        Forecast revised
        Phone Tracker forecast, shipments of                    The events of the last twelve months have
        smartphones will decline 6.5% to 1.27                   shaved 150 million units off  the market
        billion units in 2022.                                  for 2022 from our forecast in the second
                                                                quarter of 2021,” said Nabila Popal, re-
        Consumer demand lower                                   search director with IDC’s Worldwide Mo-
        The decline is due to record-breaking infl a-           bility and Consumer Device Trackers.
        tion, geopolitical tensions, and other mac-
        ro-economic challenges that have signifi -              “Despite the unit decline, average selling
        cantly dampened consumer demand.                        prices (ASPs) have grown 10% year over
                                                                year in Q2 and are forecast to grow 6.3%
        As a result, the latest forecast fi gures               for the full year.
        represent a reduction of three percentage
        points from previous projections.                       The premium segment ($800+) has
                                                                proved resilient to the economic turmoil

        However, IDC expects the setback to be                  and has grown four percentage points
        short term and the market to rebound in                 in share to 16% of the total smartphone
        2023 with 5.2% growth year over year                    market and will continue to grow.”
        and, in the long term, a fi ve-year com-
        pound annual growth rate (CAGR) of                      Foldable is fastest-growing segment
        1.4%.                                                   This includes foldable devices, which is the
                                                                fastest growing segment today and ex-

        Supply constraints have eased                           pected to increase 70% year over year in
        “The supply constraints pulling down on                 2022 to reach 13.5 million units shipped.”
        the market since last year have eased and
        the industry has shifted to a demand-con-               From a regional view, the economic crisis
        strained market.                                        has hit emerging markets, where a major-
                                                                ity of the shipment volume comes from
                                                                sub-$400 devices.


                                                                Central and Eastern Europe (CEE) is ex-
                                                                pected to be down 17.4% in 2022 and
                                                                Asia/Pacifi c (excluding Japan and China)
                                                                (APeJC), previously forecast to grow 3.0%,
                                                                is now expected to drop 4.5% in 2022.


                                                                However, the most signifi cant volume drop
                                                                is coming from China, which is now fore-
                                                                cast to decline by 12.5% or roughly 41
                                                                million units, contributing almost half of
                                       Source: IDC
                                                                                                       next page

