


Page 25 - october22_previewaa.indd
P. 25
TAP TIMES       -25                                       OCTOBER 2022


                IDC forecasts decline in                        “With economic headwinds gaining speed,
              shipments of PCs, tablets                         we expect worsening consumer sentiment
                                                                to result in further consumer market con-
        NEEDHAM, Mass. — Tumultuous times                       tractions over the next six quarters,” add-
        are ahead for the PC and tablet mar-                    ed Linn Huang, research vice president,
        kets according to a new forecast from                   Devices & Displays.
        the International Data Corporation
        (IDC) Worldwide Quarterly Personal                      Premium device market will grow
        Computing Device Tracker.                               “Economic recovery in time for the next
                                                                major refresh cycle could propel some
                                                                growth in the outer years of our forecast.
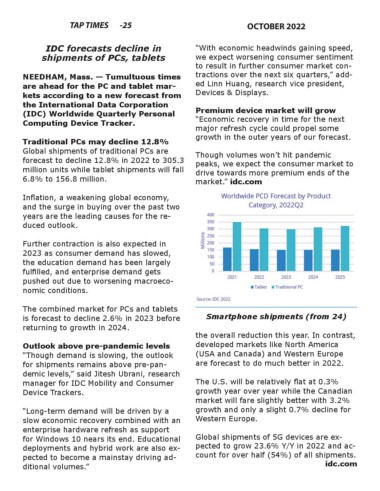
        Traditional PCs may decline 12.8%
        Global shipments of traditional PCs are                 Though volumes won’t hit pandemic
        forecast to decline 12.8% in 2022 to 305.3              peaks, we expect the consumer market to
        million units while tablet shipments will fall          drive towards more premium ends of the
        6.8% to 156.8 million.                                  market.” idc.com


        Infl ation, a weakening global economy,
        and the surge in buying over the past two
        years are the leading causes for the re-
        duced outlook.


        Further contraction is also expected in
        2023 as consumer demand has slowed,
        the education demand has been largely
        fulfi lled, and enterprise demand gets
        pushed out due to worsening macroeco-
        nomic conditions.

        The combined market for PCs and tablets
        is forecast to decline 2.6% in 2023 before                 Smartphone shipments (from 24)
        returning to growth in 2024.
                                                                the overall reduction this year. In contrast,
        Outlook above pre-pandemic levels                       developed markets like North America
        “Though demand is slowing, the outlook                  (USA and Canada) and Western Europe
        for shipments remains above pre-pan-                    are forecast to do much better in 2022.
        demic levels,” said Jitesh Ubrani, research
        manager for IDC Mobility and Consumer                   The U.S. will be relatively fl at at 0.3%
        Device Trackers.                                        growth year over year while the Canadian
                                                                market will fare slightly better with 3.2%
        “Long-term demand will be driven by a                   growth and only a slight 0.7% decline for
        slow economic recovery combined with an                 Western Europe.
        enterprise hardware refresh as support
        for Windows 10 nears its end. Educational               Global shipments of 5G devices are ex-
        deployments and hybrid work are also ex-                pected to grow 23.6% Y/Y in 2022 and ac-
        pected to become a mainstay driving ad-                 count for over half (54%) of all shipments.
        ditional volumes.”                                                                                idc.com

