


Page 29 - september22_082722.indd
P. 29
TAP TIMES       -29-                                   SEPTEMBER 2022


           Semiconductor CAPEX shows                            grated device manufacturers (IDMs) re-
                 21% growth this year                           mained well above 90% through the first
                                                                half of this year and many semiconduc-
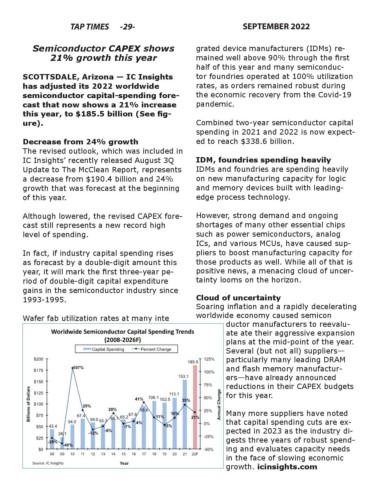
        SCOTTSDALE, Arizona — IC Insights                       tor foundries operated at 100% utilization
        has adjusted its 2022 worldwide                         rates, as orders remained robust during
        semiconductor capital-spending fore-                    the economic recovery from the Covid-19
        cast that now shows a 21% increase                      pandemic.
        this year, to $185.5 billion (See fig-
        ure).                                                   Combined two-year semiconductor capital
                                                                spending in 2021 and 2022 is now expect-
        Decrease from 24% growth                                ed to reach $338.6 billion.
        The revised outlook, which was included in
        IC Insights’ recently released August 3Q                IDM, foundries spending heavily
        Update to The McClean Report, represents                IDMs and foundries are spending heavily
        a decrease from $190.4 billion and 24%                  on new manufacturing capacity for logic
        growth that was forecast at the beginning               and memory devices built with leading-
        of this year.                                           edge process technology.

        Although lowered, the revised CAPEX fore-               However, strong demand and ongoing
        cast still represents a new record high                 shortages of many other essential chips
        level of spending.                                      such as power semiconductors, analog
                                                                ICs, and various MCUs, have caused sup-
        In fact, if industry capital spending rises             pliers to boost manufacturing capacity for
        as forecast by a double-digit amount this               those products as well. While all of that is
        year, it will mark the first three-year pe-             positive news, a menacing cloud of uncer-
        riod of double-digit capital expenditure                tainty looms on the horizon.
        gains in the semiconductor industry since
        1993-1995.                                              Cloud of uncertainty
                                                                Soaring inflation and a rapidly decelerating
        Wafer fab utilization rates at many inte                worldwide economy caused semicon
                                                                          ductor manufacturers to reevalu-
                                                                          ate ate their aggressive expansion
                                                                          plans at the mid-point of the year.
                                                                          Several (but not all) suppliers—
                                                                          particularly many leading DRAM
                                                                          and flash memory manufactur-
                                                                          ers—have already announced
                                                                          reductions in their CAPEX budgets
                                                                          for this year.

                                                                          Many more suppliers have noted
                                                                          that capital spending cuts are ex-
                                                                          pected in 2023 as the industry di-
                                                                          gests three years of robust spend-
                                                                          ing and evaluates capacity needs
                                                                          in the face of slowing economic
                                                                          growth. icinsights.com

