


Page 35 - january23_122922.indd
P. 35
TAP TIMES          -35-                                   JANUARY 2023


          Semiconductor equipment (from 34)                     pected to improve in 2024 with growth of
                                                                15.8% and 24.1%, respectively, in the test
        $14.3 billion in 2022 and 25% and 25% to                equipment and assembly and packaging
        $10.8 billion in 2023, while NAND equip-                equipment segments.
        ment sales are projected to drop 4% to
        $19.0 billion in 2022 and 36% to $12.2                  China, Taiwan and Korea are projected
        billion in 2023.                                        to remain the top three destinations for
                                                                equipment spending in 2022.
        Challenging industry conditions
        Challenging macroeconomic and semicon-                  China projected to be top spender
        ductor industry conditions are expected                 China is projected to maintain the top
        to spark a decline in back-end equipment                position next year after claiming it for the
        segment sales.                                          fi rst time in 2020, while Taiwan is expect-
                                                                ed to regain the lead in 2024.
        After registering robust 30% growth in
        2021, semiconductor test equipment mar-                 Equipment spending for all regions
        ket sales are forecast to slip 2.6% to $7.6             tracked, except Korea, are expected to
        billion in 2022 and 7.3% to $7.1 billion in             grow in 2022, though most will see a de-
        2023.                                                   crease in 2023 before returning to growth
                                                                in 2024.
        Assembly & Packaging
        Following an 87% surge in 2021, assembly                The SEMI forecast is based on collective
        and packaging equipment sales are pro-                  input from top equipment suppliers, the
        jected to drop by 14.9% to $6.1 billion in              SEMI Worldwide Semiconductor Equipment
        2022 and 13.3% to $5.3 billion in 2023.                 Market Statistics data collection program
                                                                and the industry-recognized SEMI World
        Back-end equipment expenditures are ex                  Fab Forecast database.


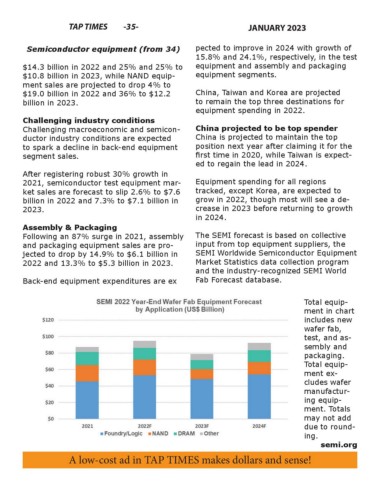
                                                                                                   Total equip-
                                                                                                   ment in chart
                                                                                                   includes new
                                                                                                   wafer fab,
                                                                                                   test, and as-
                                                                                                   sembly and
                                                                                                   packaging.
                                                                                                   Total equip-
                                                                                                   ment ex-
                                                                                                   cludes wafer
                                                                                                   manufactur-
                                                                                                   ing equip-
                                                                                                   ment. Totals
                                                                                                   may not add
                                                                                                   due to round-
                                                                                                   ing.
                                                                                                        semi.org
                       A low-cost ad in TAP TIMES makes dollars and sense!

