


Page 24 - december22_112922.indd
P. 24
TAP TIMES       -24-                                     DECEMBER 2022


                 Largest CAPEX decline                          initially forecast. Though lowered from the
               since 2008-2009 forecast                         initial outlook, the revised CAPEX forecast
                                                                will still amount to a new record high level
        SCOTTSDALE, Arizona — At the start                      of spending.
        of this year, semiconductor suppli-
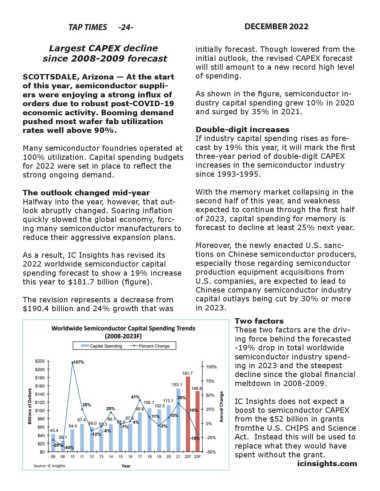
        ers were enjoying a strong infl ux of                    As shown in the fi gure, semiconductor in-
        orders due to robust post-COVID-19                      dustry capital spending grew 10% in 2020
        economic activity. Booming demand                       and surged by 35% in 2021.
        pushed most wafer fab utilization
        rates well above 90%.                                   Double-digit increases
                                                                If industry capital spending rises as fore-
        Many semiconductor foundries operated at                cast by 19% this year, it will mark the fi rst
        100% utilization. Capital spending budgets              three-year period of double-digit CAPEX
        for 2022 were set in place to refl ect the               increases in the semiconductor industry
        strong ongoing demand.                                  since 1993-1995.


        The outlook changed mid-year                            With the memory market collapsing in the
        Halfway into the year, however, that out-               second half of this year, and weakness
        look abruptly changed. Soaring infl ation                expected to continue through the fi rst half
        quickly slowed the global economy, forc-                of 2023, capital spending for memory is
        ing many semiconductor manufacturers to                 forecast to decline at least 25% next year.
        reduce their aggressive expansion plans.
                                                                Moreover, the newly enacted U.S. sanc-
        As a result, IC Insights has revised its                tions on Chinese semiconductor producers,
        2022 worldwide semiconductor capital                    especially those regarding semiconductor
        spending forecast to show a 19% increase                production equipment acquisitions from
        this year to $181.7 billion (fi gure).                   U.S. companies, are expected to lead to
                                                                Chinese company semiconductor industry
        The revision represents a decrease from                 capital outlays being cut by 30% or more
        $190.4 billion and 24% growth that was                  in 2023.

                                                                             Two factors
                                                                             These two factors are the driv-
                                                                             ing force behind the forecasted
                                                                             -19% drop in total worldwide
                                                                             semiconductor industry spend-
                                                                             ing in 2023 and the steepest
                                                                             decline since the global fi nancial
                                                                             meltdown in 2008-2009.


                                                                             IC Insights does not expect a
                                                                             boost to semiconductor CAPEX
                                                                             from the $52 billion in grants
                                                                             fromthe U.S. CHIPS and Science
                                                                             Act.  Instead this will be used to
                                                                             replace what they would have
                                                                             spent without the grant.
                                                                                                 icinsights.com

