


Page 38 - january_123021.indd
P. 38
JANUARY 2022        TAP TIMES       -38-            Foundry has accounted for the largest
                                                                share of semiconductor CAPEX each year
                                                                since 2014 with two exceptions—2017 and
            Global semiconductor equipment                      2018 when CAPEX spending for DRAM and
               CAPEX may show record high                       flash memory surged.


        SCOTTSDALE, Arizona — Worldwide                         Spending by foundries has become very
        semiconductor CAPEX is on track to                      important (and necessary) as industry de-
        surge 34% in 2021, its strongest per-                   mand continues to rise for ICs fabricated
        centage gain since a 41% increase in                    using advanced process technology nodes.
        2017, predicts IC Insights.

                                                                TSMC will spend 57% of total
        Record high                                             TSMC, the world’s largest foundry, is fore-
        The $152.0 billion in outlays in 2021                   cast to account for 57% of the $53.0 bil-
        would represent a new record high annual                lion in foundry spending this year.
        amount of spending, surpassing the pre-
        vious high mark of $113.1 billion set just              Samsung is also making significant invest-
        last year.                                              ments in its foundry operations.  Samsung
                                                                has been able to match the technology
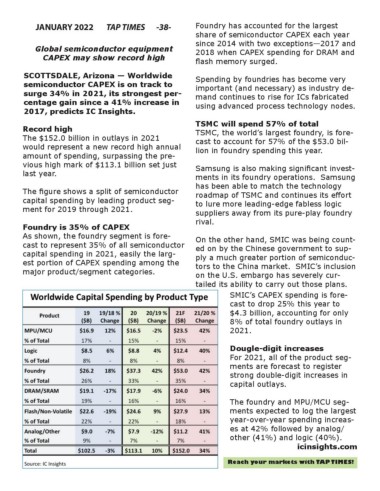
        The figure shows a split of semiconductor               roadmap of TSMC and continues its effort
        capital spending by leading product seg-                to lure more leading-edge fabless logic
        ment for 2019 through 2021.                             suppliers away from its pure-play foundry

                                                                rival.
        Foundry is 35% of CAPEX
        As shown, the foundry segment is fore-                  On the other hand, SMIC was being count-
        cast to represent 35% of all semiconductor              ed on by the Chinese government to sup-
        capital spending in 2021, easily the larg-              ply a much greater portion of semiconduc-
        est portion of CAPEX spending among the                 tors to the China market.  SMIC’s inclusion
        major product/segment categories.                       on the U.S. embargo has severely cur-
                                                                tailed its ability to carry out those plans.
                                                                           SMIC’s CAPEX spending is fore-
                                                                           cast to drop 25% this year to
                                                                           $4.3 billion, accounting for only
                                                                           8% of total foundry outlays in
                                                                           2021.

                                                                           Dougle-digit increases
                                                                           For 2021, all of the product seg-
                                                                           ments are forecast to register
                                                                           strong double-digit increases in
                                                                           capital outlays.


                                                                           The foundry and MPU/MCU seg-
                                                                           ments expected to log the largest
                                                                           year-over-year spending increas-
                                                                           es at 42% followed by analog/
                                                                           other (41%) and logic (40%).
                                                                                                 icinsights.com

                                                                          Reach your markets with TAP TIMES!

