


Page 28 - november_ 22_102722aa.indd
P. 28
TAP TIMES          -28-                               NOVEMBER 2022


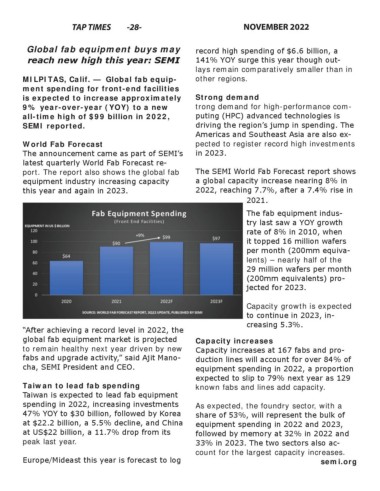
         Global fab equipment buys may                          record high spending of $6.6 billion, a
          reach new high this year: SEMI                        141% YOY surge this year though out-
                                                                lays remain comparatively smaller than in
        MILPITAS, Calif. —  Global fab equip-                   other regions.
        ment spending for front-end facilities
        is expected to increase approximately                   Strong demand
        9% year-over-year (YOY) to a new                        trong demand for high-performance com-
        all-time high of $99 billion in 2022,                   puting (HPC) advanced technologies is
        SEMI reported.                                          driving the region’s jump in spending. The
                                                                Americas and Southeast Asia are also ex-
        World Fab Forecast                                      pected to register record high investments
        The announcement came as part of SEMI’s                 in 2023.
        latest quarterly World Fab Forecast re-
        port. The report also shows the global fab              The SEMI World Fab Forecast report shows
        equipment industry increasing capacity                  a global capacity increase nearing 8% in
        this year and again in 2023.                            2022, reaching 7.7%, after a 7.4% rise in
                                                                                2021.

                                                                                The fab equipment indus-
                                                                                try last saw a YOY growth
                                                                                rate of 8% in 2010, when
                                                                                it topped 16 million wafers
                                                                                per month (200mm equiva-
                                                                                lents) – nearly half of the
                                                                                29 million wafers per month
                                                                                (200mm equivalents) pro-
                                                                                jected for 2023.


                                                                                Capacity growth is expected
                                                                                to continue in 2023, in-
                                                                                creasing 5.3%.
        “After achieving a record level in 2022, the
        global fab equipment market is projected                Capacity increases
        to remain healthy next year driven by new               Capacity increases at 167 fabs and pro-
        fabs and upgrade activity,” said Ajit Mano-             duction lines will account for over 84% of
        cha, SEMI President and CEO.                            equipment spending in 2022, a proportion
                                                                expected to slip to 79% next year as 129
        Taiwan to lead fab spending                             known fabs and lines add capacity.
        Taiwan is expected to lead fab equipment
        spending in 2022, increasing investments                As expected, the foundry sector, with a
        47% YOY to $30 billion, followed by Korea               share of 53%, will represent the bulk of
        at $22.2 billion, a 5.5% decline, and China             equipment spending in 2022 and 2023,
        at US$22 billion, a 11.7% drop from its                 followed by memory at 32% in 2022 and
        peak last year.                                         33% in 2023. The two sectors also ac-
                                                                count for the largest capacity increases.
        Europe/Mideast this year is forecast to log                                                     semi.org

