


Page 21 - foxconn preview june 25 051825_1340 hours.indd
P. 21
TAP TIMES       -21-                                  JUNE 2025

              Notebook industry remains cautious amid tariff  negotiations


        TAIPEI, Taiwan — TrendForce’s latest                    The U.S. currently maintains a 0% tariff
        research reveals that although the                      on notebooks imported from Southeast
        U.S. has granted a 90-day grace                         Asia, while imposing a 20% import duty
        period before implementing reciprocal                   on those from China.
        tariff s—off ering temporary relief
        for notebook brands—the broader                         This discrepancy has driven brands to
        market remains clouded by policy and                    accelerate shipments from Vietnam,
        economic uncertainty.                                   Thailand and other regional hubs.


        Brands began front-loading inventory in                 U.S.-based brands, having invested early
        late 2024, pushing Q4 shipment growth                   in Southeast Asia, enjoy greater fl exibility
        to 5.1%, with 1Q25 seeing a 7.2% Y/Y                    and are better positioned to replenish
        increase.                                               North American inventory during the 90-
                                                                day exemption.
        Revised forecast
        However, given persistent economic                      In contrast, non-U.S. brands, whose
        weakness and rising tariff  risks,                      Southeast Asian supply chains are still
        TrendForce has revised the full-year 2025               under development, face limited short-
        notebook brand shipment growth forecast                 term adaptability.
        downward from 3.6% to just 1.4%.
                                                                Risk of Annual Decline
                                                                The U.S. remains the world’s largest
             Materials market (from 16)                         single notebook market, accounting for
                                                                approximately 30% of global demand.
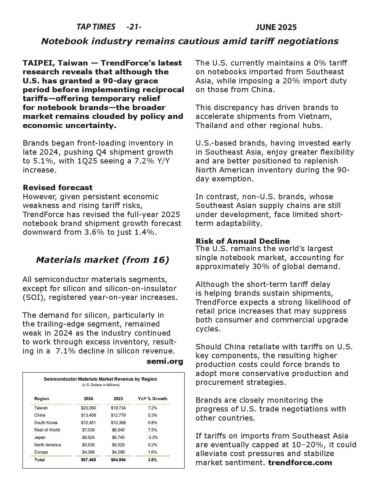
        All semiconductor materials segments,                   Although the short-term tariff  delay
        except for silicon and silicon-on-insulator
        (SOI), registered year-on-year increases.               is helping brands sustain shipments,
                                                                TrendForce expects a strong likelihood of
                                                                retail price increases that may suppress
        The demand for silicon, particularly in
        the trailing-edge segment, remained                     both consumer and commercial upgrade
                                                                cycles.
        weak in 2024 as the industry continued
        to work through excess inventory, result-
        ing in a  7.1% decline in silicon revenue.              Should China retaliate with tariff s on U.S.
                                                                key components, the resulting higher
                                                semi.org
                                                semi.org        production costs could force brands to
                                                                adopt more conservative production and
                                                                procurement strategies.


                                                                Brands are closely monitoring the
                                                                progress of U.S. trade negotiations with
                                                                other countries.


                                                                If tariff s on imports from Southeast Asia
                                                                are eventually capped at 10–20%, it could
                                                                alleviate cost pressures and stabilize
                                                                market sentiment. trendforce.com

