


Page 25 - february_012822.indd
P. 25
TAP TIMES       -25-                              FEBRUARY 2022

               China’s chip sales (from 24)                      ing to spring up in the trailing-edge fabri-
                                                                 cation field, backed by government incen-
        Equally startling is the number of new                   tives.
        firms in China rushing into the semicon-
        ductor industry.
                                                                 Mature fabrication technology
        Fabless startups                                         On the chip manufacturing front, due to
        Nearly 15,000 Chinese firms registered as                the inclusion of Huawei and SMIC on the
                                                                 U.S. government’s Entity List (China’s
        semiconductor enterprises in 2020. A large
        number of these new firms are fabless                    most advanced chip designer and foundry,
        start-ups specializing in GPU, EDA, FPGA,                respectively), the Chinese semiconductor
        AI computing, and other higher-end chip                  industry has largely suspended advanced
        design.                                                  logic node manufacturing development
                                                                 and redirected most capital to mature

        Many of these firms are developing ad-                   fabrication technology.
        vanced chips, designing and taping out
        devices on bleeding-edge process nodes.                  As a result of this change, from Septem-
                                                                 ber 2020 to November 2021, Chinese
                                                                 wafer manufacturers have added nearly
        Sales of Chinese high-end logic devices
        are also accelerating, with the combined                 500K wafer per month (WPM) capacities
        revenue of China’s CPU, GPU, and FPGA                    in trailing nodes (>=14nm), and only an
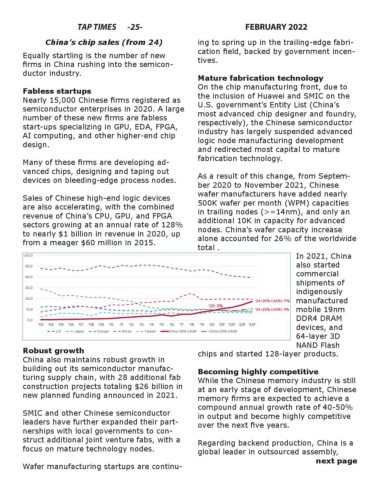
        sectors growing at an annual rate of 128%                additional 10K in capacity for advanced
        to nearly $1 billion in revenue in 2020, up              nodes. China’s wafer capacity increase
                                                                 alone accounted for 26% of the worldwide
        from a meager $60 million in 2015.
                                                                 total .
                                                                                                In 2021, China
                                                                                                also started
                                                                                                commercial
                                                                                                shipments of
                                                                                                indigenously
                                                                                                manufactured
                                                                                                mobile 19nm
                                                                                                DDR4 DRAM
                                                                                                devices, and
                                                                                                64-layer 3D
                                                                                                NAND Flash
        Robust growth                                            chips and started 128-layer products.
        China also maintains robust growth in
        building out its semiconductor manufac-                  Becoming highly competitive
        turing supply chain, with 28 additional fab              While the Chinese memory industry is still
        construction projects totaling $26 billion in            at an early stage of development, Chinese
        new planned funding announced in 2021.                   memory firms are expected to achieve a
                                                                 compound annual growth rate of 40-50%
        SMIC and other Chinese semiconductor                     in output and become highly competitive
        leaders have further expanded their part-                over the next five years.
        nerships with local governments to con-
        struct additional joint venture fabs, with a             Regarding backend production, China is a
        focus on mature technology nodes.                        global leader in outsourced assembly,
                                                                                                       next page
        Wafer manufacturing startups are continu-

